Collision and comprehensive insurance are often discussed together, but they protect your vehicle against different types of damage. Collision coverage generally helps when your car is damaged in a crash. Comprehensive coverage handles many losses that happen without a typical traffic collision, such as theft, hail, fire, vandalism, or a falling tree. Understanding the difference can help you avoid paying for coverage you do not need or discovering too late that an expensive loss is not covered.
In this guide, you will learn:
- How collision and comprehensive insurance work
- What each type of coverage pays for
- What these coverages do not include
- How deductibles affect your claim payment
- Whether you need one coverage or both
- When dropping either coverage may make financial sense
If you are still learning the basics of auto insurance, read our complete beginner’s guide to car insurance. You can also explore our guide to the different types of car insurance coverage for a broader explanation of liability, collision, comprehensive, and other policy options.
What Is Collision Insurance?
Collision insurance helps pay to repair or replace your own vehicle when it is damaged in a covered collision. It may apply when your car:
- Hits another vehicle
- Hits a tree, fence, guardrail, or utility pole
- Is damaged in a single-car accident
- Rolls over
- Hits a pothole and suffers covered physical damage
Collision coverage usually applies regardless of who caused the accident. However, the way a claim is handled may depend on fault, state rules, policy terms, and whether another driver’s insurance is responsible for the damage.
Example of a Collision Claim
Suppose you lose control of your car on a wet road and hit a guardrail. Your vehicle requires $7,000 in repairs. If you have collision coverage with a $1,000 deductible, your insurer may pay up to $6,000 for the covered repairs. You would be responsible for the first $1,000. If you only carry liability insurance, damage to your own car would generally not be covered in this situation.
What Does Collision Insurance Cover?
Collision coverage is designed for physical damage caused by your vehicle striking another vehicle or object, or by the vehicle overturning.
Common covered situations may include:
- Rear-ending another car
- Being involved in a multi-vehicle accident
- Backing into a concrete post
- Sliding into a roadside barrier
- Crashing into a building or fence
- Rolling the vehicle during a single-car accident
Your insurer will review the accident, your policy limits, the cost of repairs, your deductible, and the vehicle’s current value before determining the claim payment.
What Collision Insurance Does Not Usually Cover
Collision coverage does not protect against every type of vehicle damage.
It generally does not cover:
- Theft
- Vandalism
- Hail or flood damage
- Fire
- Falling trees or objects
- Normal wear and tear
- Mechanical breakdowns
- Damage intentionally caused by the policyholder
- Medical expenses or injuries
- Damage you cause to another person’s vehicle
Damage to other people and their property is handled through liability insurance, while many non-collision losses involving your own vehicle fall under comprehensive coverage.
What Is Comprehensive Insurance?
Comprehensive insurance helps pay for damage to your vehicle caused by many events other than a typical collision. It is sometimes called “other than collision” coverage. Comprehensive insurance commonly applies to losses involving:
- Vehicle theft
- Vandalism
- Fire
- Hailstorms
- Flooding
- Windstorms
- Falling trees or branches
- Broken or damaged glass
- Contact with animals
- Certain natural disasters
Example of a Comprehensive Claim
Imagine your car is parked outside during a severe storm. A large tree branch falls onto the roof and causes $5,000 in damage. This is not a traffic collision, so collision insurance would generally not apply. If you have comprehensive coverage with a $500 deductible, your insurer may pay up to $4,500 for the covered repairs. You would pay the first $500.
What Does Comprehensive Insurance Cover?
Comprehensive insurance protects against several risks that drivers cannot always prevent. Common examples include:
Theft
If your vehicle is stolen and not recovered, comprehensive insurance may pay its actual cash value, minus your deductible and subject to the terms of your policy.
Vandalism
Damage such as broken windows, scratched paint, or deliberately damaged body panels may be covered by comprehensive insurance.
Weather Damage
Comprehensive coverage may help pay for damage caused by hail, floods, windstorms, lightning, or falling objects during severe weather.
Fire
If your vehicle is damaged or destroyed by a covered fire, comprehensive insurance may help pay for repairs or compensate you if the vehicle is declared a total loss.
Animal Damage
Hitting a deer or another animal is generally handled as a comprehensive claim rather than a collision claim.
However, swerving to avoid an animal and crashing into a tree would normally be treated as a collision claim because the vehicle struck an object.
Glass Damage
Comprehensive insurance may cover a cracked or shattered windshield. Deductible rules for glass claims vary by insurer, policy, and state.
What Comprehensive Insurance Does Not Usually Cover
Although comprehensive coverage protects against many risks, it does not cover every loss.
It generally does not pay for:
- Damage from crashing into another car or object
- Injuries to you or your passengers
- Damage you cause to another person’s property
- Routine maintenance
- Mechanical failures
- Normal deterioration and wear
- Personal belongings stolen from inside the vehicle
Personal belongings may instead be covered by a homeowners or renters insurance policy, depending on the circumstances, policy limits, and deductible.
Are Collision and Comprehensive Part of Full Coverage?
Yes. The term full coverage usually refers to a policy that combines:
- Liability insurance
- Collision coverage
- Comprehensive coverage
Full coverage is not a standardized policy and does not mean that every possible loss is covered. Optional protections such as uninsured motorist coverage, Personal Injury Protection, rental reimbursement, roadside assistance, and gap insurance may need to be purchased separately. For a detailed explanation, read our guide to liability vs. full coverage car insurance.
Are Collision and Comprehensive Insurance Required?
Collision and comprehensive insurance are generally not required by state law. State insurance laws usually focus on liability coverage or another approved form of financial responsibility because liability insurance protects other people when you cause an accident. However, a bank, credit union, or leasing company will commonly require both collision and comprehensive coverage when you finance or lease a vehicle. The lender has a financial interest in the car until the loan is repaid. Requiring physical damage coverage helps protect that interest if the vehicle is damaged, stolen, or totaled. Once you own the vehicle outright, you can usually decide whether keeping collision and comprehensive coverage still makes financial sense.
Collision vs. Comprehensive Insurance: Key Differences
Although collision and comprehensive insurance both protect your own vehicle, they apply to very different situations. The easiest way to remember the difference is this:
- Collision insurance covers damage when your vehicle collides with another vehicle or object.
- Comprehensive insurance covers damage caused by events other than a typical collision, such as theft, hail, fire, vandalism, or falling trees.
Neither coverage replaces liability insurance. Instead, they work alongside liability coverage to provide broader financial protection for your vehicle.
Collision vs. Comprehensive Insurance Comparison Table
| Feature | Collision Insurance | Comprehensive Insurance |
|---|---|---|
| Covers damage to your own vehicle | ✅ Yes | ✅ Yes |
| Vehicle collision | ✅ Yes | ❌ No |
| Single-car accident | ✅ Yes | ❌ No |
| Vehicle rollover | ✅ Yes | ❌ No |
| Theft | ❌ No | ✅ Yes |
| Fire | ❌ No | ✅ Yes |
| Flood damage | ❌ No | ✅ Yes |
| Hail damage | ❌ No | ✅ Yes |
| Falling trees | ❌ No | ✅ Yes |
| Animal collisions | ❌ No | ✅ Yes |
| Usually required by lenders | ✅ Yes | ✅ Yes |
Real-Life Examples of Collision Claims
Understanding real-world situations makes it easier to know when collision coverage applies.
Example 1: Rear-End Accident
You’re driving home from work and accidentally rear-end another vehicle at a traffic light. Your front bumper, hood, and headlights are damaged.
Coverage: Collision insurance may help pay to repair your vehicle after your deductible is applied.
Example 2: Backing Into a Pole
While leaving a parking garage, you accidentally back into a concrete support pillar. Your rear bumper and trunk sustain significant damage.
Coverage: Collision insurance generally applies because your vehicle struck a fixed object.
Example 3: Sliding Into a Guardrail
Heavy rain causes your vehicle to lose traction, and you slide into a roadside guardrail.
Coverage: Collision insurance usually covers the damage because your vehicle collided with an object.
Real-Life Examples of Comprehensive Claims
Comprehensive insurance covers many unexpected events that happen even when your vehicle isn’t being driven.
Example 1: Vehicle Theft
You wake up one morning and discover your vehicle has been stolen from your driveway.
Coverage: Comprehensive insurance may reimburse you for the vehicle’s actual cash value if it isn’t recovered, subject to your policy terms and deductible.
Example 2: Hailstorm Damage
A severe hailstorm dents your roof, hood, and trunk while your vehicle is parked outside.
Coverage: Comprehensive insurance generally covers weather-related damage like hail.
Example 3: Falling Tree Branch
A large tree branch falls onto your parked vehicle during a windstorm.
Coverage: Comprehensive insurance typically applies because the damage wasn’t caused by a traffic collision.
Example 4: Hitting a Deer
While driving at night, a deer suddenly runs into the roadway and strikes your vehicle.
Coverage: Contact with an animal is generally handled under comprehensive coverage.
However, if you swerve to avoid the deer and crash into a tree instead, that damage is typically handled under collision coverage.
How Deductibles Work
Both collision and comprehensive insurance usually include a deductible. A deductible is the amount you agree to pay before your insurance company contributes toward a covered claim. Common deductible options include:
- $250
- $500
- $1,000
- $1,500
Choosing a higher deductible generally lowers your monthly premium, while choosing a lower deductible usually increases your premium.
Example
Your vehicle suffers $6,500 in covered collision damage.
- Total repair cost: $6,500
- Your deductible: $1,000
- Insurance payment: Up to $5,500
The same principle generally applies to comprehensive claims involving theft, hail, fire, or vandalism.
Do You Need Both Collision and Comprehensive Insurance?
Not every driver needs both coverages, but many do. You may benefit from carrying both collision and comprehensive insurance if you:
- Own a newer vehicle
- Drive a vehicle worth several thousand dollars
- Have a car loan or lease
- Depend on your vehicle every day
- Would struggle to pay for major repairs or replacement
- Live in an area with frequent severe weather or vehicle theft
On the other hand, drivers with older vehicles that have very little market value may decide that paying for both coverages is no longer cost-effective. As your vehicle ages, compare its current value with the annual cost of collision and comprehensive insurance. This can help you determine whether keeping both coverages still provides good value.
Can You Buy One Without the Other?
In many cases, yes.
Insurance companies often allow drivers to purchase comprehensive coverage without collision coverage, depending on the insurer and policy. For example, someone living in an area with a high risk of theft or hail damage may choose comprehensive coverage even if they decide not to carry collision coverage. However, if your vehicle is financed or leased, your lender will typically require you to maintain both coverages until the loan is paid in full.
Which Coverage Is More Important?
Neither coverage is universally more important because they protect against different risks. If you’re more concerned about accidents involving other vehicles or fixed objects, collision coverage offers valuable protection. If you are worried about theft, hailstorms, flooding, vandalism, or falling objects, comprehensive coverage helps protect against those risks. For many drivers, carrying both coverages provides the most complete protection for their vehicle and reduces the financial impact of unexpected events.
How Much Do Collision and Comprehensive Insurance Cost?
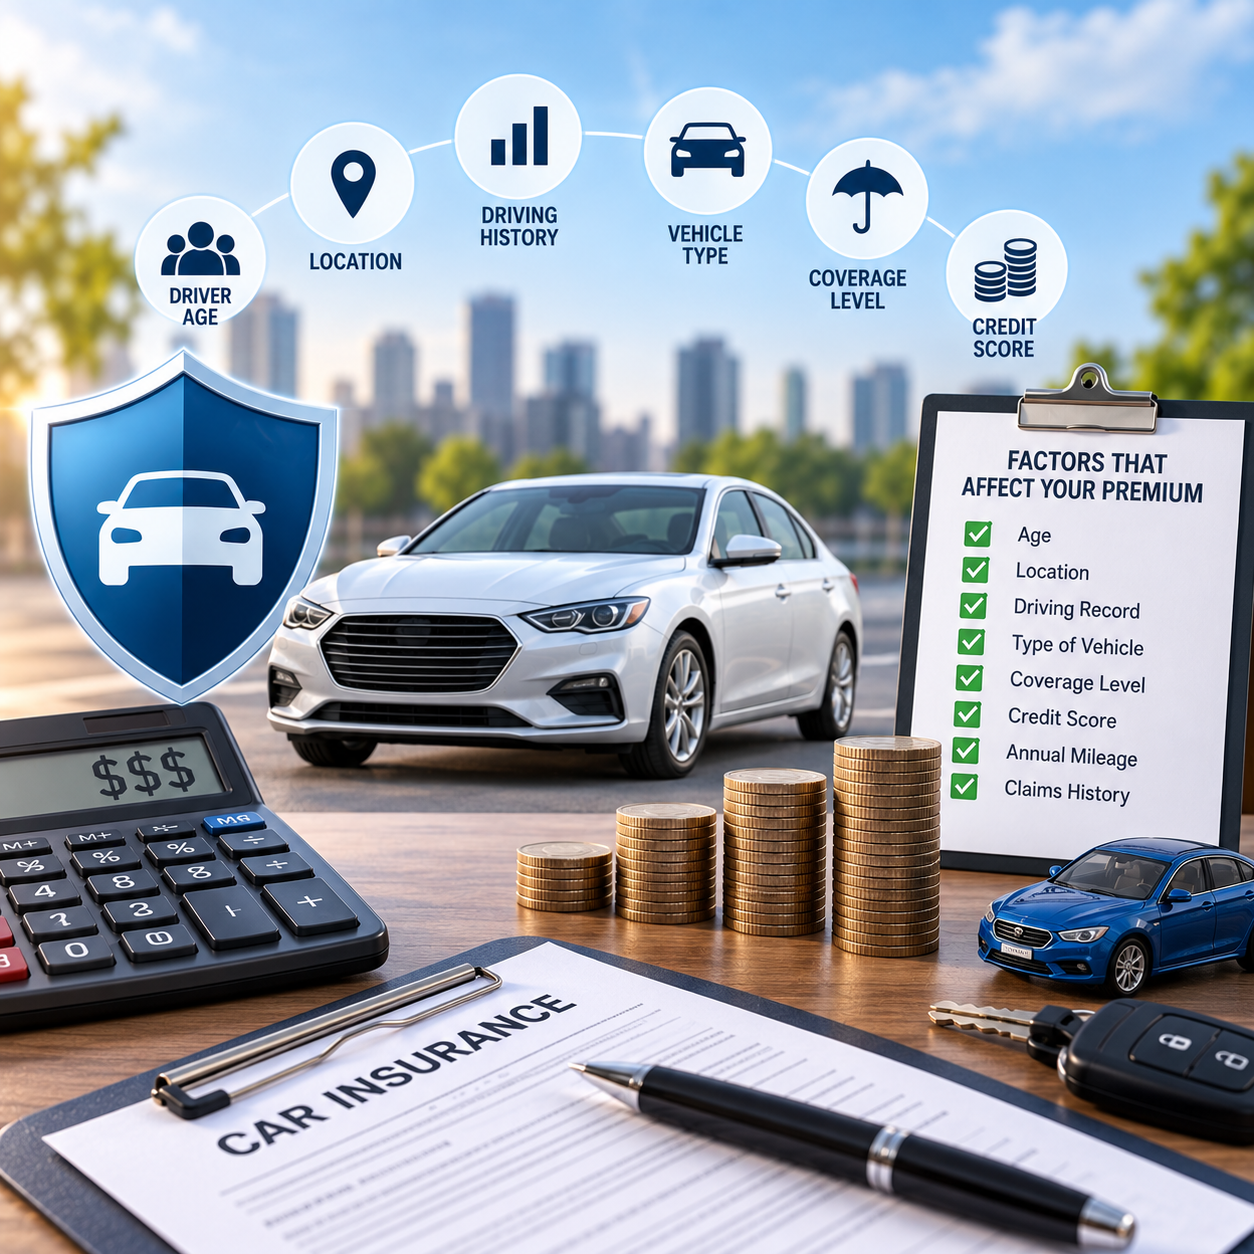
The cost of collision and comprehensive insurance varies from one driver to another. There isn’t a single price that fits everyone. Your premium depends on several factors, including:
- Your age and driving experience
- Your driving record
- Your ZIP code and state
- The make, model, and value of your vehicle
- Your annual mileage
- Your chosen deductible
- Your previous insurance claims
In general, collision coverage tends to cost more than comprehensive coverage because accidents occur more frequently than theft, fire, or weather-related claims. However, the exact difference depends on your insurer and personal circumstances.
Pros and Cons of Collision Insurance
Pros
- Helps pay to repair or replace your vehicle after a covered accident.
- Provides financial protection even if you’re at fault.
- Often required for financed or leased vehicles.
- Can prevent large out-of-pocket repair expenses.
Cons
- Increases your monthly insurance premium.
- Usually requires you to pay a deductible before coverage applies.
- May not be worthwhile for older vehicles with low market value.
Pros and Cons of Comprehensive Insurance
Pros
- Protects against theft, vandalism, fire, hail, floods, and many other non-collision events.
- Provides peace of mind for drivers living in high-risk areas.
- Helps protect the value of newer vehicles.
- May cover damage caused by falling objects or animal collisions.
Cons
- Adds to your overall insurance premium.
- Claims are generally subject to a deductible.
- Does not cover damage caused by traffic collisions.
Quick Decision Guide
| Your Situation | Collision | Comprehensive |
|---|---|---|
| New vehicle | ✅ Recommended | ✅ Recommended |
| Financed or leased vehicle | ✅ Usually Required | ✅ Usually Required |
| Older vehicle with low value | ⚠️ Consider Dropping | ⚠️ Depends on Risk |
| Area with frequent hail or flooding | Optional | ✅ Recommended |
| High vehicle theft area | Optional | ✅ Recommended |
| Daily commuter | ✅ Recommended | ✅ Recommended |
Final Verdict: Collision vs. Comprehensive Insurance
Collision and comprehensive insurance are not competing coverages they’re complementary. Collision insurance protects your vehicle when it’s damaged in an accident involving another vehicle or object. Comprehensive insurance protects against many unexpected events that occur outside of normal driving, including theft, fire, vandalism, hail, floods, and falling objects. If your vehicle is newer, financed, leased, or still has significant value, carrying both coverages often provides the strongest financial protection. If your vehicle is older and worth only a small amount, you may decide that paying for both coverages is no longer cost-effective. Review your policy regularly and compare the annual premium with your vehicle’s current market value before making changes.
Conclusion
Choosing the right auto insurance isn’t just about meeting legal requirements it’s about protecting yourself from unexpected financial losses. Understanding the difference between collision and comprehensive insurance makes it easier to build a policy that matches your vehicle, your budget, and your personal level of risk. Before changing your coverage, consider your vehicle’s value, your deductible, where you live, and how easily you could afford major repair or replacement costs.
At PolicyHelpUSA, we believe insurance should be easy to understand. Our guides are written to help U.S. drivers compare coverage options, avoid costly mistakes, and make confident insurance decisions based on facts not confusing industry jargon.
Frequently Asked Questions (FAQs)
Can I have comprehensive insurance without collision insurance?
In many cases, yes. Some insurance companies allow you to purchase comprehensive coverage without collision coverage. However, financed or leased vehicles typically require both.
Does collision insurance cover hitting a deer?
Usually no. If your vehicle strikes a deer or another animal, the damage is generally covered under comprehensive insurance. However, if you swerve to avoid the animal and crash into a tree or guardrail, that damage is typically handled under collision coverage.
Do I need both collision and comprehensive insurance?
Many drivers benefit from carrying both coverages, especially if their vehicle has significant value or they could not comfortably afford major repair or replacement costs.
Is collision insurance required by law?
No. State laws generally require liability insurance, not collision coverage. However, lenders often require collision insurance for financed or leased vehicles.
Does comprehensive insurance cover engine failure?
No. Mechanical breakdowns, normal wear and tear, and routine maintenance are generally not covered by comprehensive insurance.
Can I remove collision coverage after paying off my car?
Yes. Once you own your vehicle outright, you can usually choose whether to keep or remove collision coverage. Before making that decision, compare your vehicle’s value with the cost of maintaining the coverage.